

U.S. Large-Cap Stocks Lead the Way
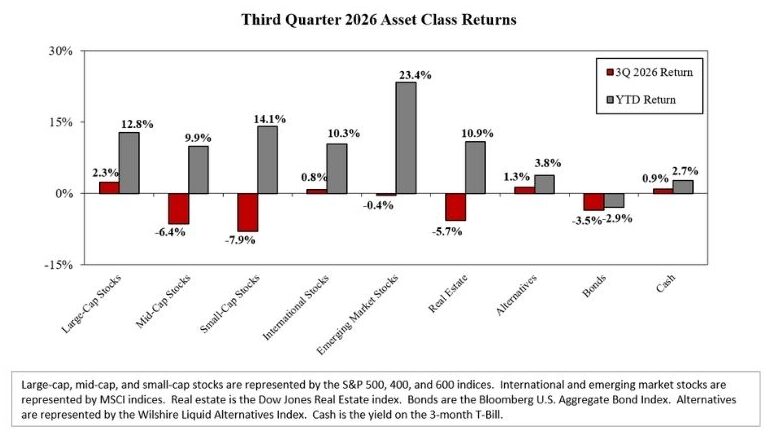
While the S&P 500 gained a modest 2.3% for the quarter, that masked a lot of volatility in other parts of the stock market. Mid-cap and small-cap stocks both saw significant declines, and international stocks were basically flat. Large-cap stocks reemerged as the leader after trailing small-cap and emerging market stocks considerably in the first half of the year. One reason is that small-cap earnings tend to be much more sensitive to a rising rate environment. Small-cap stocks were down 7.9% in the quarter but are still outperforming their large-cap counterparts for the year.
Artificial intelligence remained a prominent driver in large-cap stock returns. Several mega-cap stocks rebounded from a slow start to the year, as Microsoft, NVIDIA, Apple, and Meta Platforms all posted double-digit returns for the quarter. While these stocks helped boost the technology industry in general, they still trailed energy stocks, which led sector returns at over 16% in the quarter and over 40% on the year, thanks to the increase in fuel prices.
Bonds Struggle, Alternatives Continue to Shine
Higher bond yields hurt returns for the asset class this quarter, as the aggregate bond index fell 3.5%. Rising yields have created a challenging environment for bond investors since the start of the decade, with the aggregate bond index posting a negative return over the previous five years. Prospects for a continued rise in bond yields mean bonds will pay higher rates of income in the future, but also that prices may continue to come down. Bonds are an important safety buffer, but their returns have left much to be desired.
While bond returns have been poor during this period, our alternative investment strategies have done quite well. These investments, like bonds, can help hedge the risk of the stock market, but they have managed to earn far better returns than bonds. The managed futures and style premia funds each generated returns well into double digits this year. Catastrophe bonds have also performed well, which makes sense given the remarkably quiet hurricane season in the Atlantic. Alternative lending and multi-strategy funds haven’t delivered returns as strong as the others. Still, even these strategies have outpaced bonds considerably both for the year and since the start of the decade.
Over the past several years, the alternatives portfolio has produced stock-like returns with bond-like volatility. That won’t always be the case. In fact, in the latter half of the 2010s, these alternatives faced significant scrutiny over their performance. However, we continued to use these strategies because of their unique sources of risk and returns and because they can serve as important diversifiers when added to a traditional investment portfolio. So, while this asset class may one day face challenging times again (as does any asset class), we maintain our long-term, diversified approach grounded in academic research.
There is a lot to worry about in today’s capital markets, but the economy remains robust and diversified portfolios have earned historically strong returns. With today’s high stock market valuations, volatility is likely here to stay, but that is not a reason to change course. Balanced portfolios with stocks, bonds, and alternative investments should offer a strong solution to long-term wealth creation even if there are a few speed bumps along the way.